Hit by an Uninsured or Hit-and-Run Driver in Kansas: What to Do and Who Pays
If an uninsured driver hit you in Kansas, or the driver who caused the crash fled and was never identified, your own auto policy may be the source that pays for your injuries, through what is called uninsured motorist (UM) coverage. UM coverage sits on your own policy and is built for exactly this situation: the at-fault driver had no liability insurance, or cannot be found. Instead of trying to collect from a driver who has nothing or cannot be identified, you generally look to your own insurer. What you do in the first few days, especially reporting the crash and notifying your own insurer, can decide whether that claim gets paid. Empower Injury Law handles these cases for drivers and passengers in Lawrence, Douglas County, and the surrounding area, including Eudora and Baldwin City.
What to do right after a crash with an uninsured driver
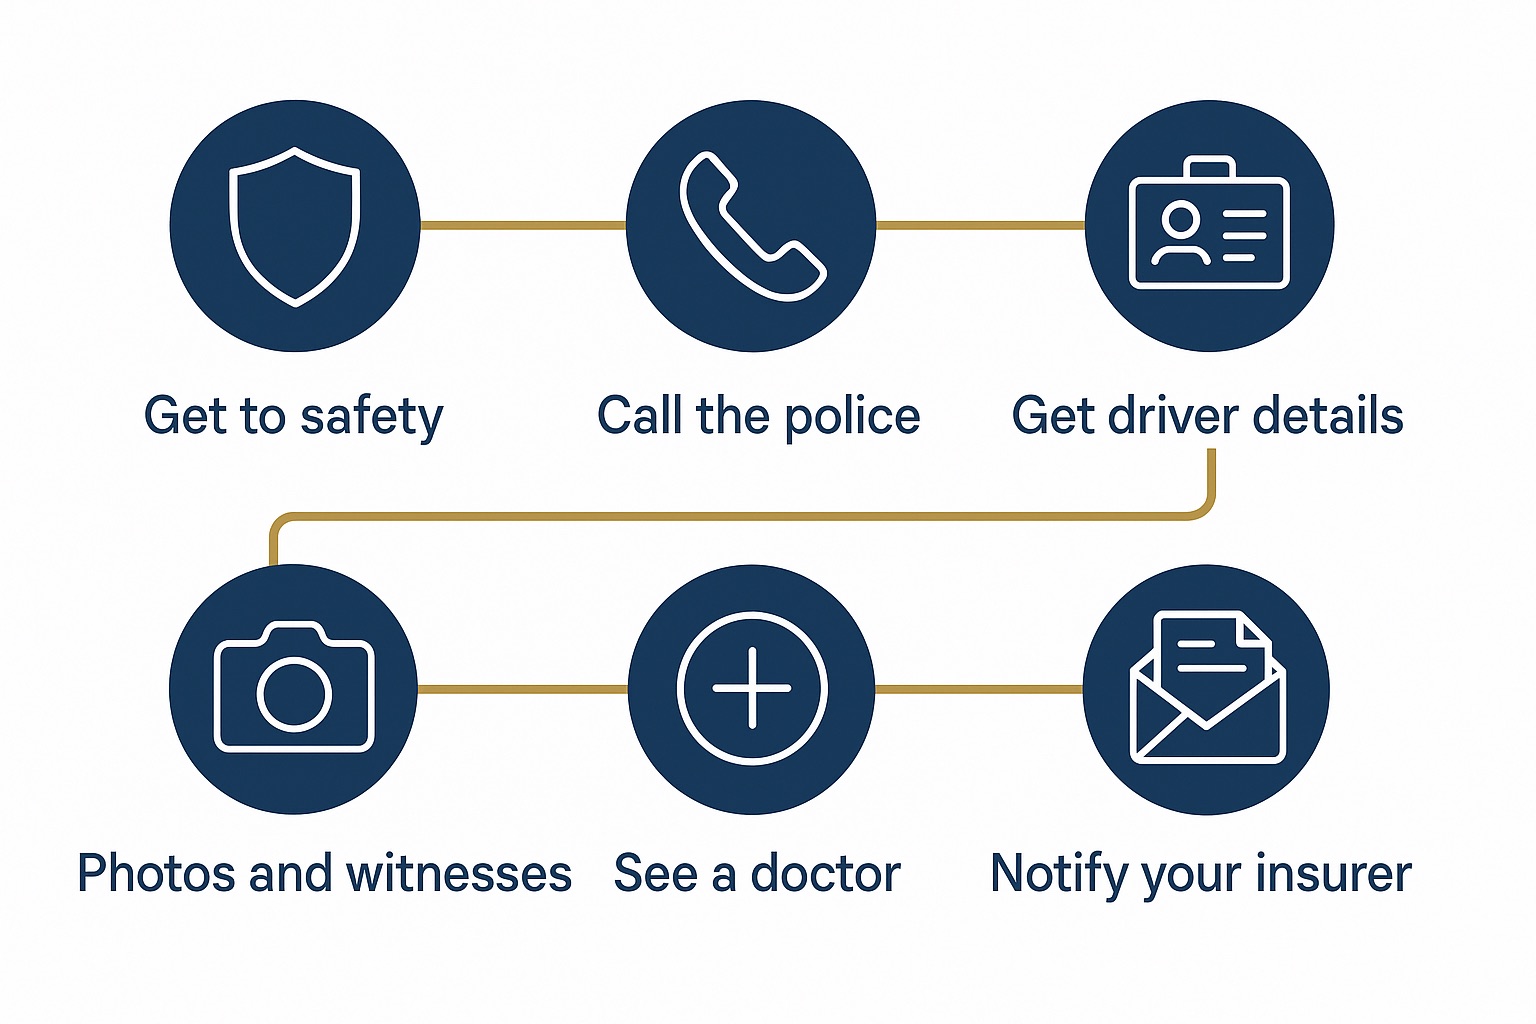
The steps after a crash with an uninsured driver are mostly the same as any crash, with a few that matter more here because the other driver may have nothing to offer and may try to leave.
- Get to safety and check for injuries. If anyone is hurt, call 911. Federal crash guidance from NHTSA is simple on this point: get out of traffic if you safely can, and get medical help first.
- Call the police and let them document the scene. A police report is often the only neutral record of what happened, and it matters more than usual when the other driver has no insurance or leaves the scene.
- Get the other driver's information if you can, including name, license, plate, and any insurance card, even one that looks expired or invalid.
- Take photos of the vehicles, the scene, the road, and your visible injuries. Get the names and numbers of any witnesses, because in a hit-and-run a witness may be the only person who saw the other vehicle.
- Do not let the other driver talk you out of calling the police or into a private cash arrangement at the scene. That is a common move from someone who knows they are uninsured.
- See a doctor, even if you feel okay at first. Some injuries surface a day or two later, and a gap in treatment can become an issue later in the claim.
Once you are safe and treated, notify your own insurer that you were in a crash and that the other driver appears to be uninsured or fled. Your policy will require prompt notice, so do it as soon as you reasonably can.
What is uninsured motorist coverage, and why does it apply here?
Uninsured motorist coverage is a part of your own auto insurance policy that pays for your injuries when the at-fault driver had no liability insurance, or when the driver fled and cannot be identified. Because there is no other-driver policy to pursue, a UM claim is a claim against your own insurer under your own contract, and your insurer effectively stands in the place of the driver who should have carried insurance.
Kansas law addresses uninsured motorist coverage in K.S.A. 40-284. Kansas requires UM coverage on every auto policy, with minimum limits of $25,000 per person and $50,000 per accident. The UM limits you carry set the ceiling on what a UM claim can recover, so your own limits matter a great deal.
These two are easy to mix up. Uninsured motorist (UM) coverage applies when the at-fault driver had no liability insurance at all, or is an unidentified hit-and-run driver. Underinsured motorist (UIM) coverage applies when the at-fault driver did have insurance, but not enough to cover your injuries. If the other driver was insured but underinsured, the analysis is related but separate.
For the full picture of how UM and UIM coverage work in Kansas, including limits and how claims are handled, see our overview of uninsured and underinsured motorist coverage in Kansas.
What if it was a hit-and-run?
A hit-and-run, where the driver who caused the crash flees and is never identified, is often handled through uninsured motorist coverage, because there is no identified driver and no liability policy to pursue. Kansas, however, may apply specific conditions to a claim involving an unidentified vehicle.
Some states require that the phantom vehicle physically struck your car, or that an independent witness corroborate its existence, before a UM claim on an unidentified driver can proceed. Whether Kansas imposes such a requirement affects claims where a driver ran you off the road without touching your car and then disappeared. This rule can decide the claim, so talk to us before assuming a hit-and-run is covered, especially if the other car never touched yours.
However that rule applies to your crash, report the crash to the police promptly and get a report number, and notify your own insurer quickly. Prompt reporting matters even more than usual here, because the insurer cannot check the crash against another driver's account.
Who pays your medical bills and lost wages: PIP and UM
Kansas is a no-fault state for certain first-party benefits, which means your own auto policy includes personal injury protection (PIP) that pays some of your early medical expenses and wage loss regardless of who was at fault. That is separate from the UM claim, which is aimed at the injuries and losses the at-fault driver would have owed you.
PIP does not reduce your UM coverage limit, but UM will not pay again for losses PIP already covered (K.S.A. 40-3113a). The general point for an injured person is that PIP can start covering medical bills and some wage loss early, while the UM claim addresses the broader harm, and the two are coordinated rather than simply added together.
Kansas also uses a modified comparative fault system with a 50% bar, which means your own recovery can be reduced by your share of fault, and it can be eliminated entirely if you are found 50% or more at fault. In a clear uninsured-driver or hit-and-run crash this often is not a live issue, but it can matter when the insurer disputes how the crash happened.
Who is the uninsured driver, and can you still pursue them?
When the at-fault driver has no liability insurance, they are usually not a realistic source of money. You can sometimes still pursue an uninsured driver directly, but a person who could not afford insurance often cannot pay a judgment either, which is much of the reason UM coverage exists in the first place. Uninsured drivers are common enough that these claims are routine rather than rare. The Insurance Information Institute publishes national and state-level data on uninsured driver rates, and the figures are high enough to take your own UM limits seriously.
If a rideshare trip was involved, whether you were a passenger, the rideshare driver, or hit by one, the available coverage can work differently, so mention the rideshare trip when you call.
What not to do after an uninsured-driver crash
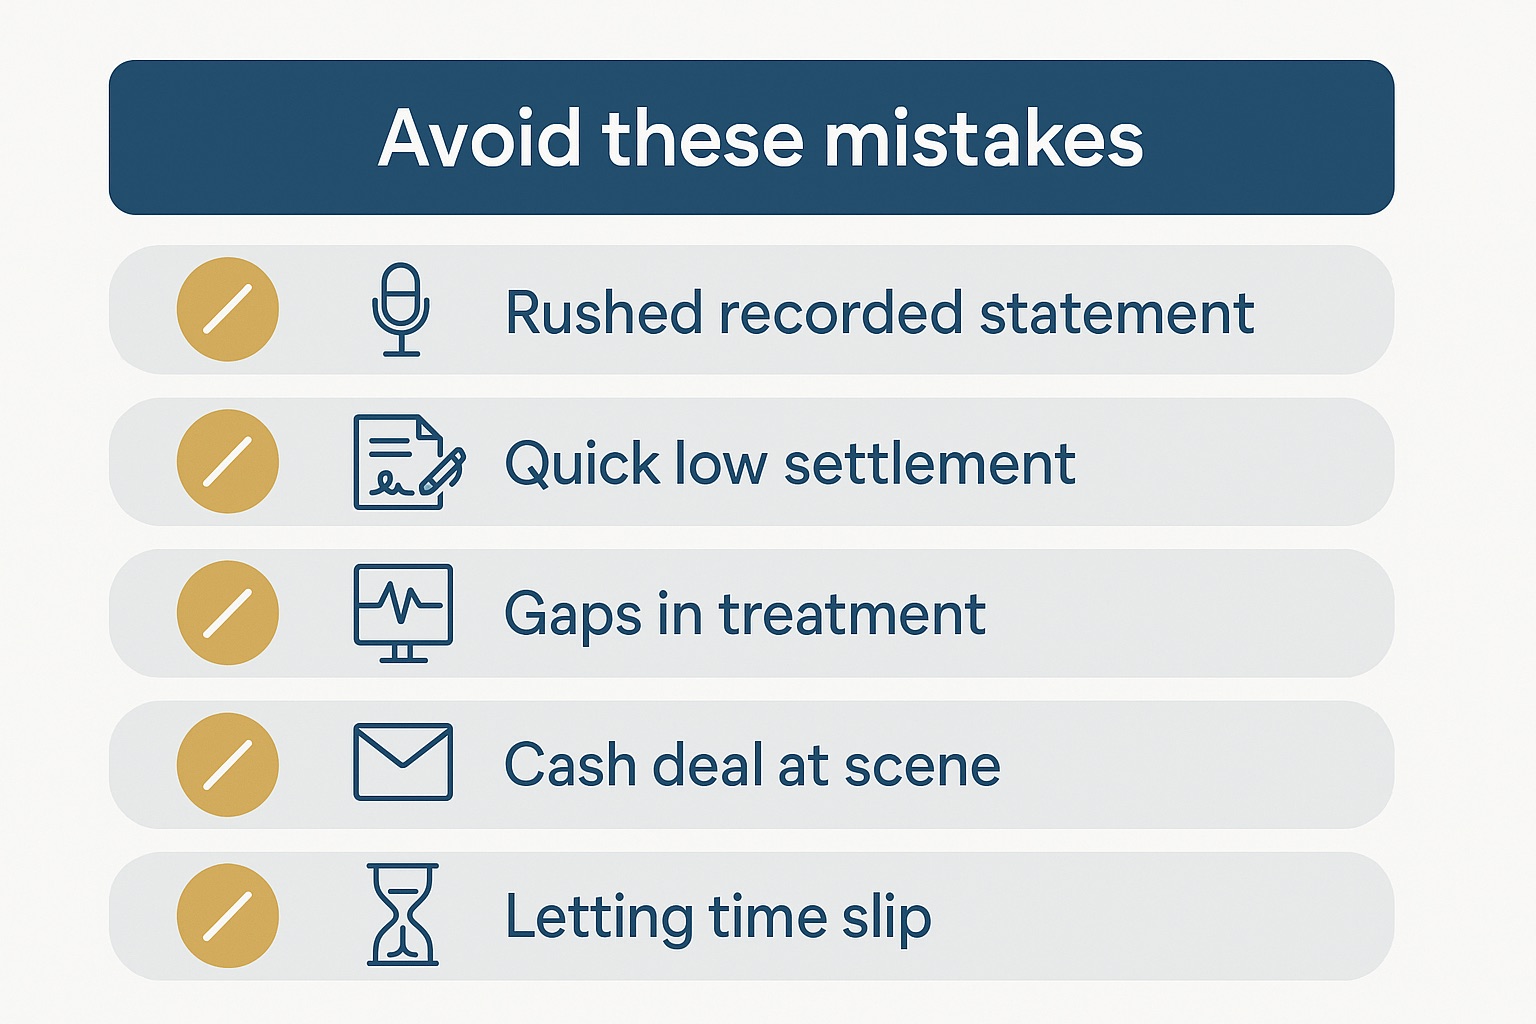
A few avoidable mistakes come up again and again in these claims:
- Do not give a recorded statement under pressure before you understand what is being asked. Your own insurer may ask for one as part of a UM claim, and your policy may include a duty to cooperate, but you can prepare or speak with a lawyer first. Adjusters take recorded statements early for a reason, and an offhand comment can be used to minimize the claim later.
- Do not accept a fast, low settlement before you know the full extent of your injuries. Some injuries take time to show, and once you settle you generally cannot reopen the claim.
- Do not skip or delay medical treatment. Gaps in treatment are routinely used to argue that an injury was not serious or was not caused by the crash.
- Do not assume you have no options just because the other driver was uninsured or fled. UM coverage exists precisely for this situation.
- Do not let the deadline sneak up. Most Kansas personal injury claims must be filed within 2 years under K.S.A. 60-513, and a UM claim carries its own timing rules on top of that, so treat the matter as time-sensitive. Our guide to the Kansas statute of limitations covers the deadlines in detail.
How Empower Injury Law can help
If an uninsured or hit-and-run driver hurt you in Lawrence, Douglas County, or a nearby community like Eudora or Baldwin City, you can talk it through with us at no cost. We will review your own policy to confirm your UM coverage and limits, coordinate your PIP benefits, deal with the adjuster and any recorded-statement request, and watch the deadlines so a notice or reporting requirement does not cut off the claim. We work on a contingency fee, so there is no fee unless there is a recovery.
Call the Lawrence office at 785-367-6937, or request a free case review through the form on this page. For the broader process on a Kansas crash claim, see our Lawrence, KS car accident lawyer page, and for injuries generally, our Lawrence personal injury lawyer page. You can also find plain-language client videos on our YouTube channel.
This page is general information about Kansas law, not legal advice, and it does not create an attorney-client relationship. Coverage questions turn on the wording of your policy and the facts of your claim. If you have questions about yours, call our Lawrence office at 785-367-6937.
Frequently asked questions
Who pays if an uninsured driver hits me in Kansas?
Often your own uninsured motorist (UM) coverage pays. Because the at-fault driver had no liability insurance, you generally file the claim with your own insurer under your own policy, up to your UM limits, rather than trying to collect from a driver who has no coverage. Your recovery cannot exceed the UM limits you carry.
Is a hit-and-run covered by uninsured motorist coverage in Kansas?
A hit-and-run is often handled through uninsured motorist coverage, because there is no identified driver and no liability policy to pursue. Kansas may apply specific conditions to a claim involving an unidentified phantom vehicle, though, so talk to us before assuming a hit-and-run is covered.
What is the difference between uninsured and underinsured motorist coverage in Kansas?
Uninsured motorist (UM) coverage applies when the at-fault driver had no liability insurance at all, or is an unidentified hit-and-run driver. Underinsured motorist (UIM) coverage applies when the at-fault driver had insurance, but not enough to cover your injuries. Both are claims against your own insurer.
Does my PIP coverage pay after an uninsured-driver crash in Kansas?
Kansas is a no-fault state for certain first-party benefits, so your own policy's personal injury protection (PIP) can pay some early medical expenses and wage loss regardless of fault. How PIP coordinates with a UM claim on the same crash depends on Kansas rules and your policy, so ask us how it applies to yours.
How long do I have to bring a claim after an uninsured-driver crash in Kansas?
Most Kansas personal injury claims must be filed within 2 years under K.S.A. 60-513, and a UM claim can carry its own separate timing rules under your policy. Because the timelines differ and can be strict, treat the claim as time-sensitive from the start.
Should I give the insurance company a recorded statement?
You are not required to give a rushed recorded statement before you understand the request. Your own insurer may ask for one as part of a UM claim, and your policy may include a duty to cooperate, but it is reasonable to prepare or talk to a lawyer first so an early comment is not used to minimize your claim.
Author Bio
Kevin A. Jones | Personal Injury Lawyer
Kevin A. Jones, founder and managing attorney of Empower Injury Law, has been practicing law since 2009. With over $25 million in jury verdicts and settlements in his first decade, Kevin has earned a reputation as a fierce advocate for his clients.
Kevin’s approach to law is rooted in his passion for helping people who have been mistreated by corporations, insurance companies, and other powerful entities.
Whether representing individuals wronged by negligent drivers or those injured on someone else’s property, Kevin is dedicated to achieving justice. His extensive experience in the courtroom ensures that clients receive strong, personalized representation that delivers results.
Practice Areas


